How near-bankruptcy forced the reforms that made modern India
In the summer of 1991, India was so broke that it did the thing every Indian family dreads most. It pawned its gold.
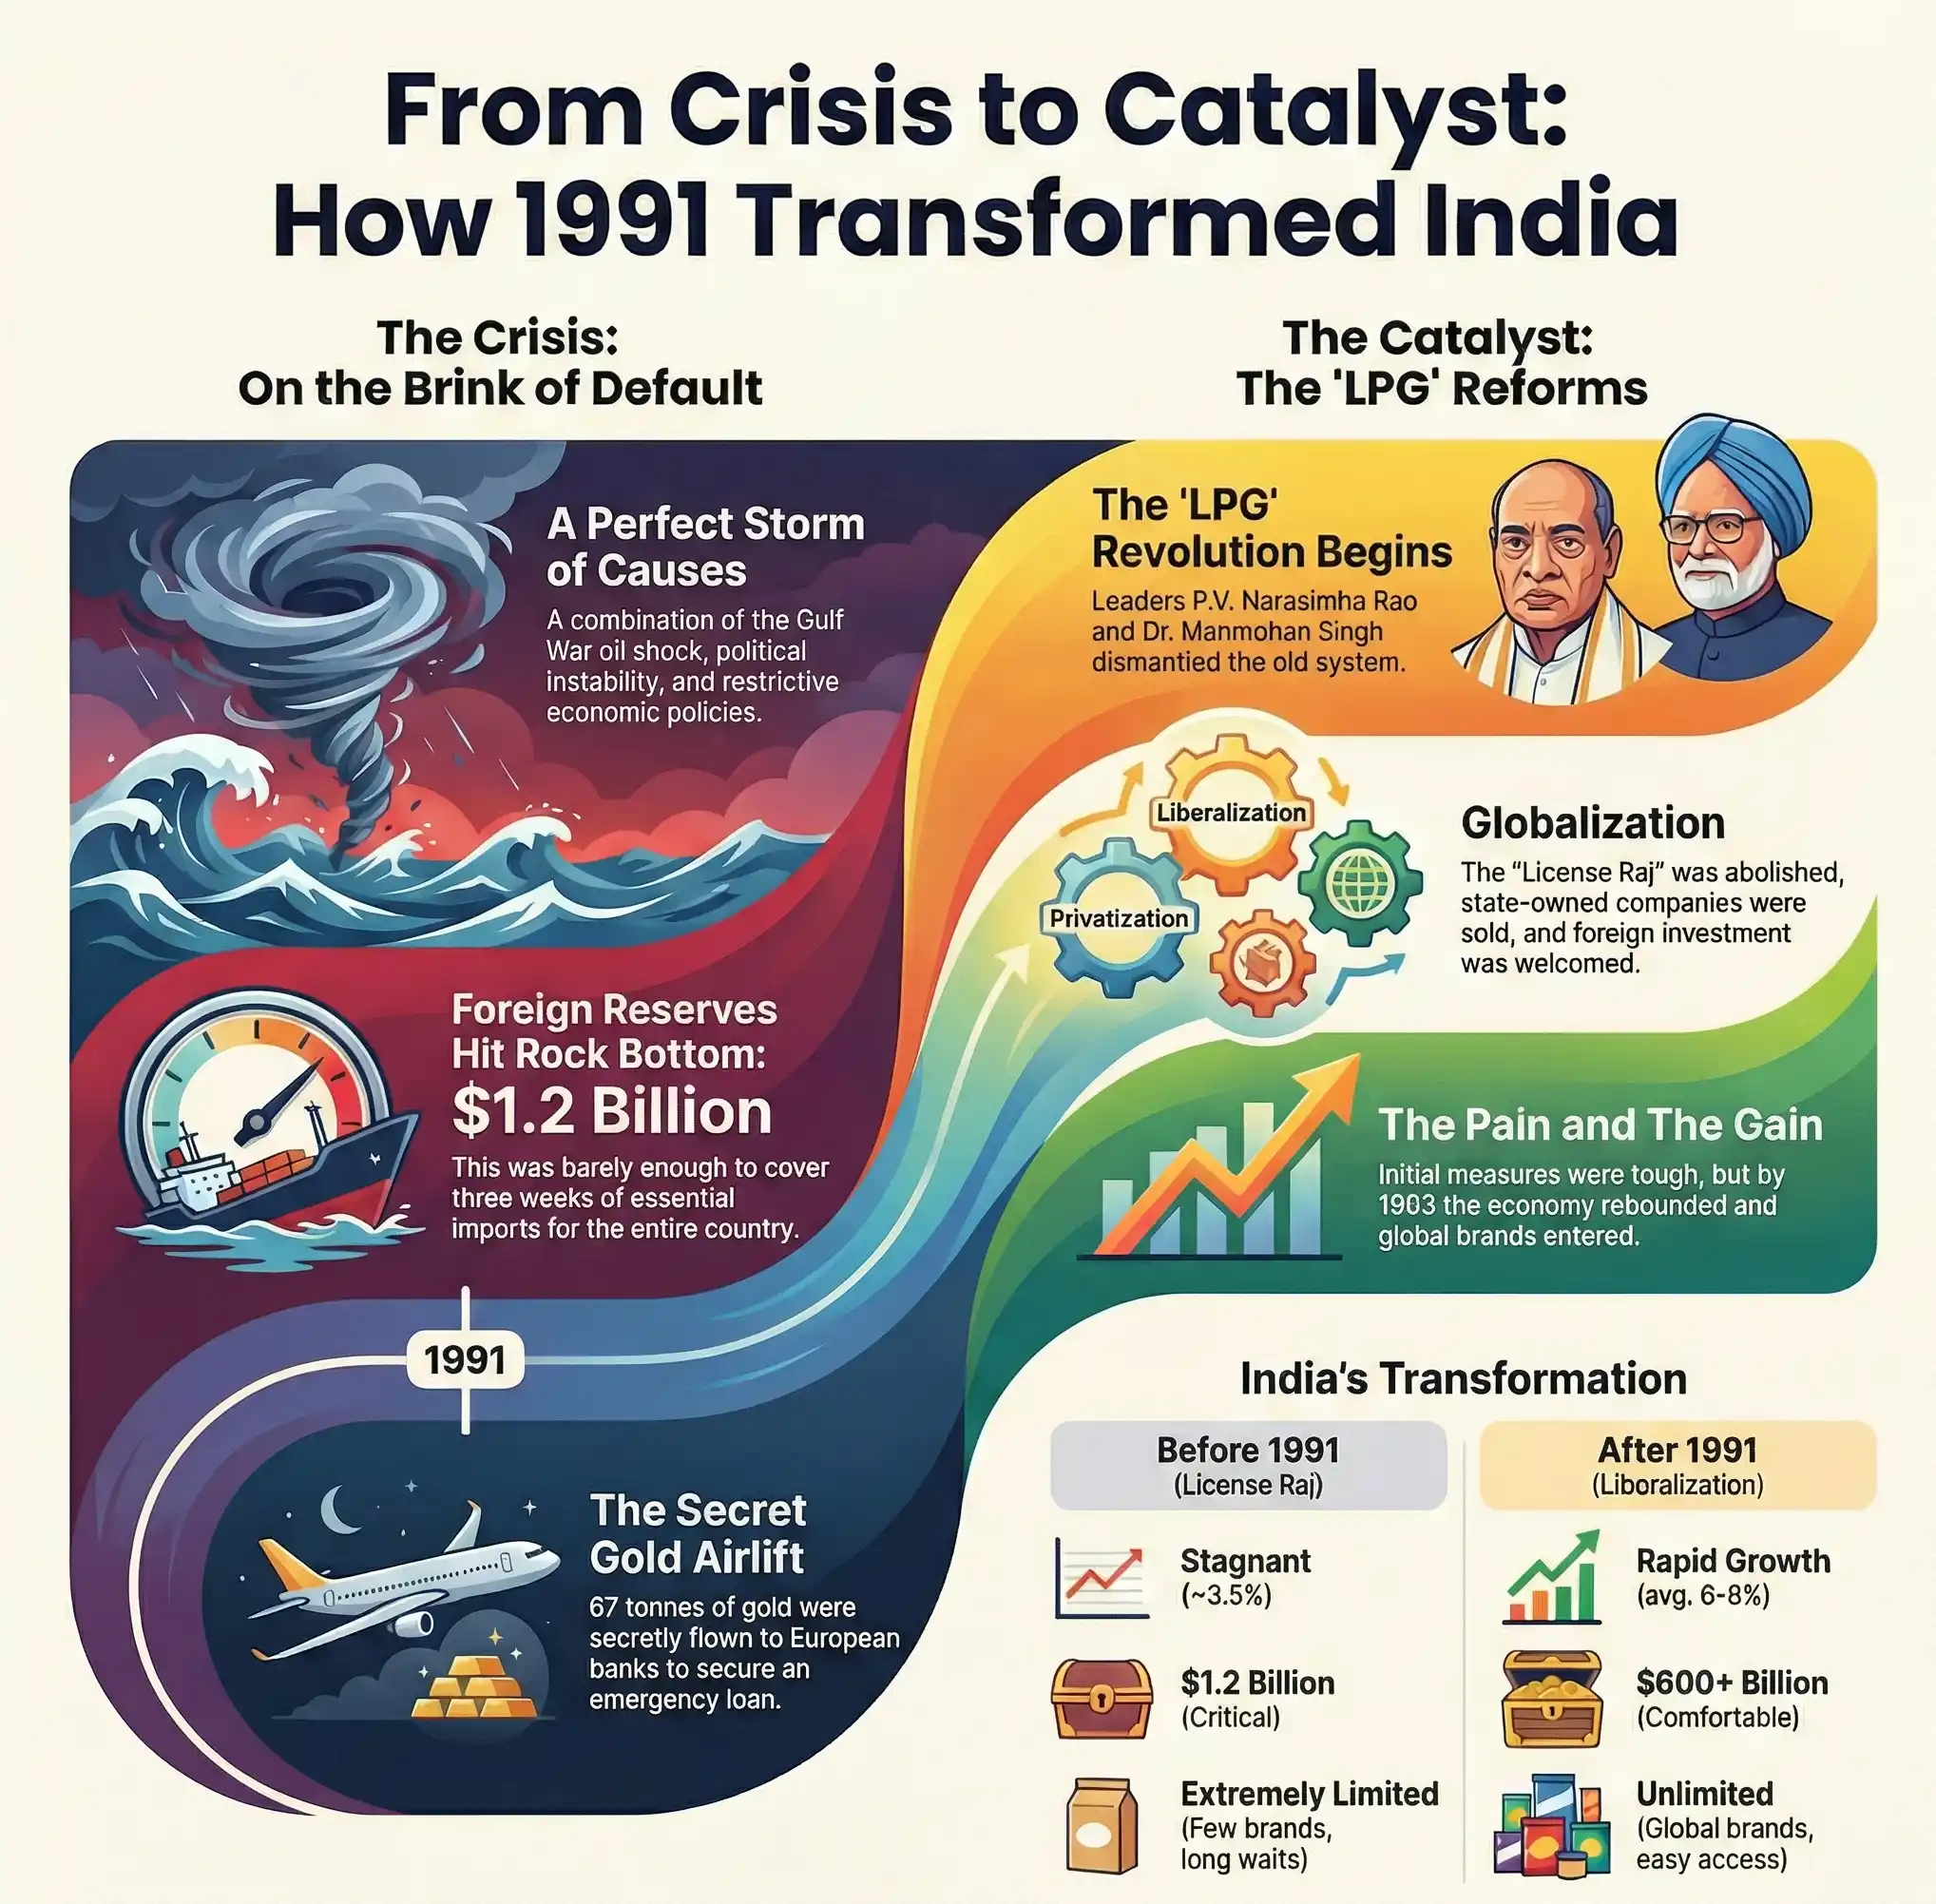
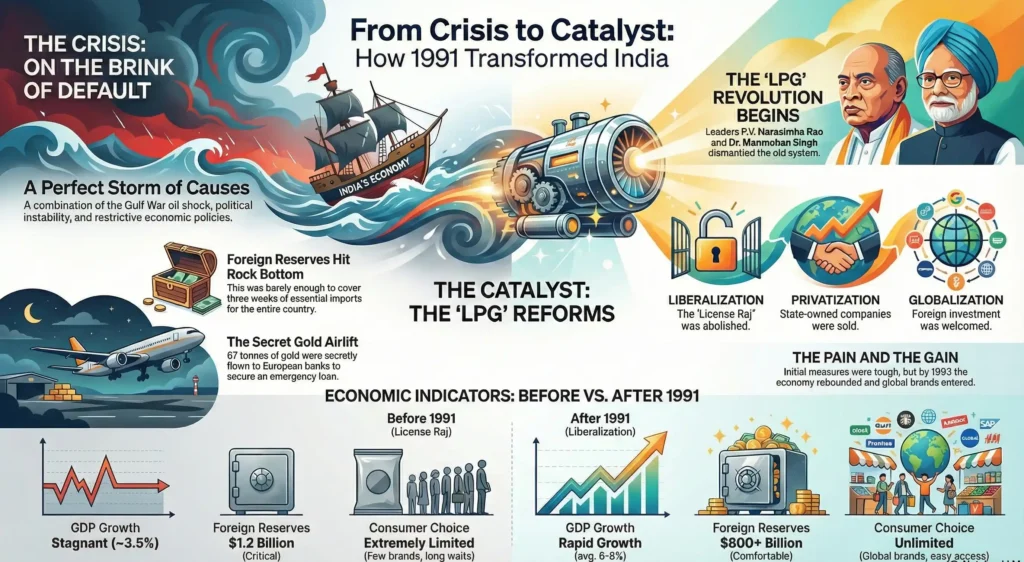
In the dead of night, under armed guard and the strictest secrecy, tonnes of the nation’s gold reserves were quietly loaded onto planes and flown out of the country, to be mortgaged to banks in London and Switzerland. India had simply run out of foreign money, run out of the dollars it needed to buy the oil and the food and the essentials to keep going. It was days, perhaps only weeks, from failing to pay its debts and being declared, before the whole world, bankrupt.
In a culture where pawning the family gold is the last and most shameful resort of a household in ruin, a nation doing the same was a humiliation almost too deep to speak of.
And yet that catastrophe was also, strangely, the beginning of the rescue. Because the disaster of 1991 finally forced India to do the thing that forty years of plain good sense had failed to make it do: to tear down the well-meant system that had kept it poor. This is the story of how a nation, saved by its own near-ruin, remade itself in a matter of weeks, and of the honest question that has hung over it ever since: remade for whom?
The cage of good intentions
To understand the rescue, you first have to understand why India was so poor in the first place, because it was not for any lack of talent or effort.
For four decades after independence, India had run a tightly controlled, state-directed economy, and it had done so on genuinely idealistic foundations. The founders believed that in a poor country freshly freed from an empire that had drained it, the government and not the market should hold the commanding heights, and should protect ordinary people from being exploited all over again. It was a noble idea.
But over the years it had hardened into something suffocating, a system remembered as the License Raj. To start a business, to make a product, to build a factory or even to expand one, an entrepreneur needed to gather a mountain of government permits, and the waiting could take years. Ordinary people waited years for a telephone connection, and years to buy a scooter. It was a cage built with good intentions, and inside it a brilliant, enterprising people sat trapped in scarcity and sluggish growth.
It was a cage built out of good intentions. And inside it, one of the most enterprising peoples on earth sat trapped for forty years in shortage and slow decline.
The Roopkund Skeleton Lake Mystery: Why Were Greeks Dying in the Indian Himalayas?
The perfect storm
By 1991, that slow weakness collided with a run of sharp bad luck, and the whole structure buckled.
In 1990, the Gulf War sent the price of oil soaring, and India’s import bills with it. At the same time, the many Indians working in the Gulf fled the fighting and came home, cutting off the money they had been sending back. India’s politics, meanwhile, was in chaos, with three governments in barely two years, which frightened away the foreign lenders the country had been leaning on. The reserves of foreign currency drained away until barely a billion dollars was left, enough to pay for only two or three weeks of imports.
India stood two or three weeks away from running out of money entirely. That was how close the edge was when the gold was flown out in the dark.
The accidental PM and the quiet economist
The men who met that moment were about the least likely revolutionaries anyone could have chosen.
The new Prime Minister was P.V. Narasimha Rao, an ageing, cautious, deeply scholarly politician who had been all but preparing to retire from public life when the top job unexpectedly fell to him. To run the economy, instead of a seasoned politician, Rao reached for an economist who had never once won an election: a soft-spoken, turbaned academic named Manmohan Singh. Rao gave him the cover he would need with a wry and honest promise: if the reforms worked, the party would take the credit, and if they failed, Singh alone would be sacked.
Two of the mildest men in all of Indian public life, a retiring old scholar and an economist who had never won a vote, were about to blow up forty years of orthodoxy in a single afternoon.
1971 Nagarwala Case: India’s Great Bank Heist Mystery
The idea whose time had come
On 24 July 1991, Manmohan Singh stood up in Parliament and presented a budget that quietly dismantled the old world.
The License Raj was swept away. Businesses would no longer need the government’s blessing simply to exist and to grow. India threw open its long-closed doors to foreign investment and to global trade, and slashed the taxes that had walled its market off from the world. The currency was devalued to make Indian exports competitive again. The whole package came to be known by three words: liberalisation, privatisation and globalisation.
Singh ended his speech with a line borrowed from Victor Hugo, and it has echoed down the years since. No power on earth, he said, can stop an idea whose time has come.
From scarcity to plenty
The change, when it came, was faster and larger than almost anyone had dared to hope.
Within a few years the economy was surging. Foreign companies poured in with their products and their factories. The great software boom took root in Bangalore and Hyderabad, and a country the world had written off became one of its coming powers. The chronic shortages that had shaped daily life simply melted away. A nation of endless waiting lists became a nation of dizzying choice. Growth roughly doubled.
And beneath the glossy surface of new cars and new brands, something far more important was happening. A vast new middle class rose up. And over the decades that followed, hundreds of millions of Indians, by many estimates more than two hundred and seventy million people, climbed up and out of absolute poverty.
Whatever else can be said about it, the reform of 1991 improved the material lives of more human beings, for the better, than almost any single policy in the history of the modern world.
That is not a small thing. It is one of the great achievements of independent India.
8 Defining Chapters in the Vikram Sarabhai Biography
Remade for whom?
But an honest telling cannot end on the mountaintop, because the tide that rose in 1991 did not lift every boat, and it would be dishonest to pretend it did.
The dazzling new growth flowed most strongly to the cities, to the educated, to those who were already standing in a position to reach out and seize the new opportunities. India’s villages and its hundreds of millions of farmers, fully half the country, were mostly left on the shore, watching the wave roll past them. The gap between the shining new rich and the same old poor widened, in places, into a chasm. And the freeing of enterprise, for all its energy, also opened the door to a grubbier game, in which the well-connected sometimes prospered less through brilliance than through influence.
The old scarcity was gone. But a sharp new inequality quietly moved in to take its place, and India has been wrestling with it ever since.
The country had been set loose to grow. It had not yet worked out how to make that growth reach everyone.
Saved by the catastrophe
So what is the deepest lesson of 1991?
The obvious one is heroic, and it is true. In its darkest hour, with the right handful of people in the right place, a great nation found the nerve to remake itself, and it worked. But there is a harder lesson lying just beneath that one, and it is the one worth carrying away.
India did not reform in 1991 because it had at last been convinced that its old ways were mistaken. It had known that, in truth, for years. It reformed because catastrophe had finally stripped away every other option. The change that would go on to transform a billion lives was made not out of wisdom, but out of sheer desperation, standing on the very lip of ruin.
India did not change because it had grown wise. It changed because disaster had left it no other way out. That, more often than we like to admit, is how the largest changes come, to nations and to people alike.
There is a quiet tragedy in that, when you think of all the needless poverty and waiting and want that a whole generation was made to endure in the long years before the crisis forced the obvious. And there is an unfinished task in it too, the one that 1991 handed on to every year since. It is to do the far harder thing that no crisis can ever force a country to do: to make sure that the plenty those frantic weeks unleashed reaches not only the fortunate few in the gleaming glass cities, but the farmer, the labourer, and the child in the distant village, who are still, quietly, waiting for their share of the future that India once pledged its gold to buy.
The Purulia Arms Drop Mystery 1995: When the Sky Rained Guns
If you think you have remembered everything about this topic take this QUIZ
Results


#1. What was the ‘perilous’ status of India’s foreign exchange reserves in mid-1991 that triggered the emergency gold airlift?
#2. How did the Indian government secure an emergency loan to prevent a total economic default in 1991?
#3. What external geopolitical event in 1990-91 acted as a major trigger for India’s Balance of Payments crisis?
#4. The 1991 reforms are famously summarized by the acronym ‘LPG’. What does the ‘L’ stand for in this context?
#5. Who was the Finance Minister that presented the historic 1991 Budget and famously quoted Victor Hugo?
#6. According to the ‘Quick Comparison’ table, what was the ‘Hindu Rate of Growth’ that characterized the pre-1991 era?
#7. What was the ‘License Raj,’ and how did the 1991 reforms change it?
#8. What was the weight of the gold airlifted in 1991, which the text compares to a Boeing 737 aircraft?
What triggered the 1991 economic crisis in India?
The crisis was triggered by a high fiscal deficit and a Balance of Payments crisis. The Gulf War of 1990 caused oil prices to spike and stopped remittances, leaving India with critically low foreign reserves.
What is the LPG model introduced in 1991?
LPG stands for Liberalization (removing restrictions on business), Privatization (reducing government role), and Globalization (integrating with the world economy).
Who was the Prime Minister during the 1991 reforms?
P.V. Narasimha Rao was the Prime Minister. He is often called the “Father of Indian Economic Reforms” for his political will to back the changes.
Did India sell its gold in 1991?
India did not sell the gold permanently; it pledged (mortgaged) it to the Bank of England and the Union Bank of Switzerland to secure an emergency loan. The gold was later reclaimed.
What was the famous quote by Manmohan Singh in 1991?
He quoted Victor Hugo: “No power on earth can stop an idea whose time has come,” referring to India’s emergence as a major economic power.
Sources & References
- Reserve Bank of India (the 1991 balance-of-payments crisis and the gold pledge) — the crisis and the emergency measures taken to avoid default.
- International Monetary Fund (India’s 1991 crisis) — the near-default and the reform programme that followed.
- Union Budget archive, Government of India (the 1991-92 budget speech) — the reforms as Manmohan Singh announced them.
- Encyclopaedia Britannica (“P.V. Narasimha Rao” and India’s economy) — the leaders behind the reforms and the transformation they set off.
Author


Exploring the Soul of Bharat through History, Science, Culture, and its Diversity
Our Mission
Curious Indian is a definitive knowledge portal dedicated to chronicling the events, personalities, and cultural shifts that defined the Indian subcontinent. From the ancient Vedic Period to the complexities of 21st-century politics, our goal is to provide deep-dive analysis that inspires.
Editorial Standards & E-E-A-T
Every article published under our brand undergoes a rigorous fact-checking process. We prioritize primary historical records, academic citations, and credible archives to ensure our readers receive accurate, high-authority information.
Historical Integrity Directly sourcing from ASI archives and academic journals.Topical Authority Comprehensive clustering of Indian Science, Biographies, and Wars.Managed by Paripurna Datta and TEAM | Dedicated to the Knowledge of India.